
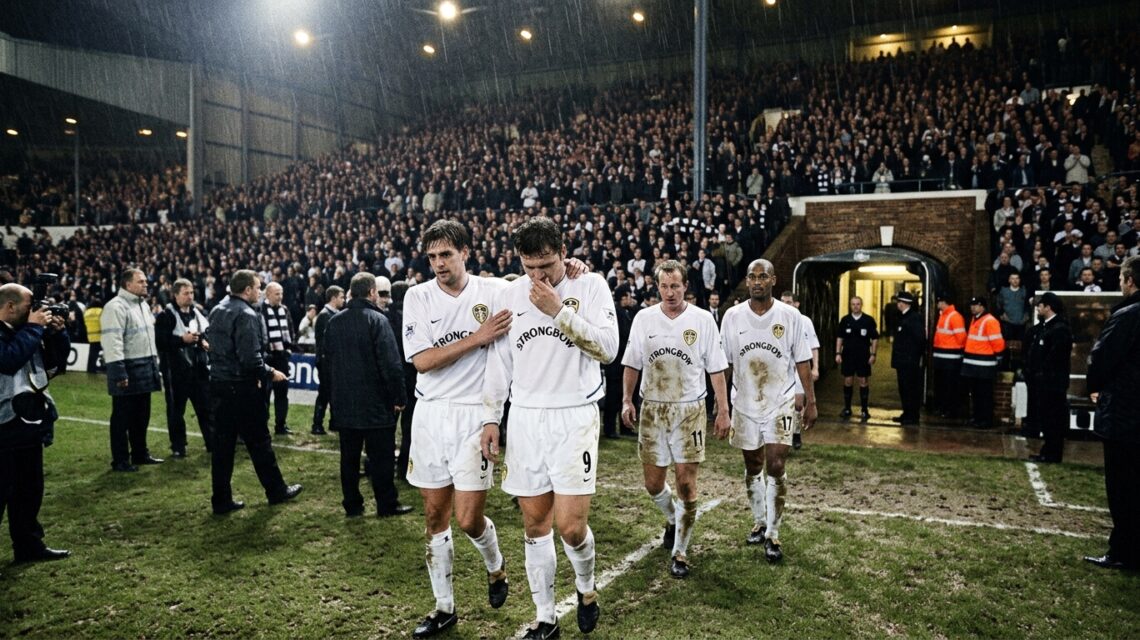
Peter Ridsdale’s ambitious spending plan turned a promising young team into a European contender. But missing the Champions League exposed a debt crisis that forced Leeds to sell its stars, lose its stadium and endure 16 years outside the Premier League.
By Marcio Tamer
Updated October 31, 2026
In May 2001, Leeds United were just two matches away from reaching the Champions League final. Their squad included Rio Ferdinand, Harry Kewell, Alan Smith and Mark Viduka, and the club appeared capable of becoming a permanent member of European football’s elite.
Three years later, Leeds were relegated from the Premier League with debts that had exceeded £100 million.
By 2007, they had entered administration and fallen into the third tier of English football for the first time in their history.
The collapse was not caused by a single disastrous transfer or one missed Champions League qualification.
It was the result of a financial structure that depended on sporting success continuing.
Under chairman Peter Ridsdale, Leeds committed to expensive players, rising wages and long-term borrowing while expecting repeated appearances in Europe’s most lucrative club competition.
One of the most revealing arrangements was a £60 million bond secured against future season-ticket sales and matchday receipts.
That debt would have to be serviced whether Leeds qualified for the Champions League or not.
When the club finished fifth in the Premier League in 2002, the expected European income failed to arrive. The wage bill and financial obligations remained.
What followed was a destructive cycle of player sales, falling sporting performance and shrinking revenue.
The club that had challenged Europe’s best teams in 2001 was playing third-division football six years later.
How Leeds became a Champions League contender
Leeds United entered the 1990s with a recent league title and ambitions to return to European prominence.
The club won England’s First Division in 1991-92, the final season before the Premier League was established.
But that achievement did not produce a sustained period of dominance.
Leeds experienced inconsistent results during the following years.
The appointment of David O’Leary as manager in 1998 helped change the team’s direction.
O’Leary inherited a promising group of young players, several developed through the club’s academy.
Harry Kewell, Alan Smith and Jonathan Woodgate emerged as important members of the squad.
They were joined by experienced players such as Nigel Martyn and David Batty.
The club also spent heavily to strengthen its team.
Mark Viduka arrived from Celtic in 2000.
Rio Ferdinand joined from West Ham United later that year in a transfer worth approximately £18 million, a British record for a defender at the time.
Leeds were building a squad that combined young talent, international experience and expensive acquisitions.
The results initially justified the optimism.
In 1999-2000, Leeds reached the UEFA Cup semifinals.
They also finished third in the Premier League, qualifying for the Champions League.
The following season, they reached the semifinals of Europe’s leading club competition.
The team was young, ambitious and increasingly competitive.
For supporters, the future appeared extraordinarily promising.
For the club’s directors, that success encouraged a more dangerous assumption: European qualification could become a reliable source of future income.
The 2001 Champions League run encouraged a risky financial strategy
Leeds’ 2000-01 Champions League campaign was remarkable.
They advanced through two group stages in a competition that included some of Europe’s strongest clubs.
Their opponents included Barcelona, AC Milan, Real Madrid and Lazio.
Leeds eventually reached the semifinals against Valencia.
The Spanish club won the tie 3-0 on aggregate.
The defeat ended Leeds’ hopes of reaching the final.
But the campaign had already demonstrated the team’s potential.
It also brought substantial revenue from European television rights, matchday income and UEFA distributions.
That money helped support the club’s growing expenditure.
The problem was that Leeds began operating as though similar income would continue arriving.
A Champions League appearance is not guaranteed.
Qualification depends on league performance, and even strong teams can miss out.
Leeds nevertheless committed to a cost structure that was difficult to sustain without repeated European participation.
The club’s financial strategy effectively turned sporting ambition into a revenue forecast.
That distinction would become critical.
Expected Champions League income could support a business plan.
It could not be treated as guaranteed cash.
Leeds borrowed £60 million against future ticket and stadium income
The most important financial detail is often misunderstood.
Leeds did not simply borrow money against future Champions League television payments.
The club also used long-term borrowing secured against income from its own supporters.
Contemporary reporting identified a £60 million bond with a 25-year term, backed by future season-ticket sales and gate receipts.
That arrangement gave Leeds access to money immediately.
In exchange, it committed future revenue streams to servicing the debt.
The distinction matters because those revenues would otherwise have been available to fund ordinary operations.
Borrowing against future income can be manageable when a business has stable cash flow and conservative financial commitments.
But Leeds combined that financing with aggressive spending on players and wages.
The club was effectively using money from future seasons to help fund its present ambitions.
It also entered complex player-financing arrangements.
Some players were acquired through leasing or hire-purchase structures rather than straightforward transfers paid entirely upfront.
Those agreements could reduce the immediate cash required for acquisitions.
But they created continuing financial obligations.
UEFA reported in January 2004 that Leeds still owed approximately €10 million connected to Mark Viduka’s acquisition under a complicated leasing arrangement.
The arrangement demonstrates why the crisis cannot be explained by one simple bank loan.
Leeds had accumulated several forms of financial commitments.
They included long-term debt, player-financing obligations and a wage bill that assumed a much stronger revenue base than the club ultimately maintained.
Why finishing fifth in 2002 became the turning point
The 2001-02 season began with Leeds hoping to return to the Champions League.
But their league form deteriorated.
The club eventually finished fifth.
That position was respectable by ordinary Premier League standards.
For Leeds’ financial strategy, however, it was a serious setback.
The top four clubs qualified for the following season’s Champions League.
Leeds missed out.
The club had therefore lost access to the European income that had helped justify its spending.
The consequences were not immediate bankruptcy.
Leeds still possessed valuable players, a large stadium and substantial commercial revenue.
But the underlying financial problem became more difficult to ignore.
The club had to meet commitments based on its existing contracts.
Players still needed to be paid.
Debt obligations still had to be serviced.
Transfer payments remained due.
The expected Champions League income was no longer available to support those expenses.
Leeds had built a business model with limited room for sporting disappointment.
Finishing fifth exposed that weakness.
The wage bill became one of Leeds’ biggest financial problems
The club’s spending was not limited to transfer fees.
Player wages represented a major ongoing commitment.
A transfer fee is often distributed over several accounting periods.
A salary must be paid throughout the player’s contract.
That makes high wages especially dangerous when revenue falls.
By the financial year ending June 2003, Leeds’ wage bill had reached approximately 88% of turnover, according to contemporary financial reporting.
That meant nearly nine-tenths of the club’s annual revenue was being consumed by player wages alone.
The remaining income still had to cover stadium operations, administration, financing costs and other expenses.
The club reported a pretax loss of approximately £49.5 million for the 2002-03 financial year.
Those figures revealed that the problem was structural.
Leeds were spending far more than their ordinary operations could support.
Selling one player might provide temporary relief.
But it would not necessarily solve the underlying mismatch between revenue and costs.
The club needed to reduce its commitments while also generating enough income to remain competitive.
Those two objectives increasingly conflicted.
Selling Rio Ferdinand raised £30 million but did not solve the crisis
In July 2002, Leeds sold Rio Ferdinand to Manchester United.
The fee was approximately £30 million.
At the time, it was a British transfer record.
The sale demonstrated how much value Leeds had accumulated in its squad.
Ferdinand had become one of Europe’s leading defenders.
Selling him generated a substantial amount of cash.
But the transfer also weakened the team.
The sporting consequences mattered because Leeds needed strong league results to recover its European income.
The club was now caught in a difficult position.
It needed to sell valuable players to reduce financial pressure.
But selling those players made Champions League qualification less likely.
The Ferdinand transfer also challenges the idea that every Leeds player was sold for a bargain price.
Manchester United paid a record fee.
The problem was not that Leeds received nothing for its assets.
It was that even major transfer income could not immediately resolve the scale of its financial commitments.
Other players followed Ferdinand out of Elland Road.
Robbie Keane moved to Tottenham Hotspur.
Jonathan Woodgate joined Newcastle United.
Robbie Fowler, Lee Bowyer and other established players also departed.
As the financial pressure intensified, rival clubs understood that Leeds needed to sell.
That weakened the club’s negotiating position.
The player sales created a cycle that made Leeds weaker every season
The consequences of the financial crisis extended beyond the balance sheet.
Every major departure reduced the quality or depth of the squad.
Leeds had reached the Champions League semifinals with a team capable of competing against elite European opposition.
By 2003, many of those players had gone.
The club’s results deteriorated.
After finishing fifth in 2001-02, Leeds fell to 15th in 2002-03.
They avoided relegation, but their financial problems continued.
The managerial situation also became unstable.
David O’Leary was dismissed in June 2002.
Terry Venables replaced him but departed in March 2003.
Peter Reid subsequently took charge.
Ridsdale resigned as chairman in March 2003.
The repeated changes complicated efforts to rebuild.
The club was attempting to reduce spending, manage creditors and remain competitive in the Premier League at the same time.
Each objective affected the others.
Cutting wages weakened the squad.
A weaker squad produced poorer results.
Poorer results reduced the possibility of returning to Europe.
That made the original financial commitments even harder to sustain.
The collapse became a self-reinforcing cycle.
Leeds’ debts exceeded £100 million before the 2004 rescue
The size of Leeds’ debt varied depending on the date and accounting measure used.
This is an important distinction because historical accounts often quote different figures without explaining what they represent.
In 2003, contemporary reporting described net debts of approximately £78 million.
Other reports referred to broader liabilities exceeding £100 million.
By the time a rescue consortium took control in March 2004, the club’s financial obligations were commonly reported at approximately £103 million.
The figures are not necessarily contradictory.
Net debt, total borrowings and total liabilities measure different things.
Net debt generally reflects borrowings after accounting for cash and related financial items.
Total liabilities can include additional obligations such as trade creditors and amounts owed on player transfers.
The wider financial picture was severe.
The club had reported large operating losses.
Its wage bill was exceptionally high relative to turnover.
And its ability to raise cash through player sales was diminishing.
In March 2004, a consortium led by Gerald Krasner completed a rescue transaction.
UEFA reported that creditors accepted substantially less than the full amounts owed.
The arrangement allowed the club’s operations to continue under new ownership.
But it did not restore the squad or prevent relegation.
Leeds were relegated from the Premier League in 2004
The 2003-04 season completed the sporting collapse.
Leeds struggled throughout the campaign.
Peter Reid was dismissed in November 2003.
Eddie Gray took temporary charge.
But the team could not recover.
Leeds finished 19th in the Premier League.
They were relegated to the second tier.
The result was extraordinary given the club’s position only three years earlier.
In 2001, Leeds had played in the Champions League semifinals.
In 2004, they were leaving the Premier League.
The financial consequences of relegation were also serious.
Premier League broadcasting revenue was substantially greater than income available in the second tier.
Leeds therefore faced another reduction in revenue while still dealing with the consequences of earlier commitments.
The club had entered a period in which financial and sporting decline reinforced each other.
The original ambition had been to establish Leeds permanently among Europe’s leading teams.
Instead, the club was struggling to preserve its financial survival outside England’s top division.
Why Leeds sold Elland Road and its training ground
The crisis eventually forced Leeds to dispose of assets that had long been central to the club’s identity.
In 2004, Leeds sold Elland Road, their historic stadium.
The transaction was structured with an option to repurchase the ground.
The club also sold its Thorp Arch training facility.
These decisions were intended to generate immediate cash and reduce financial pressure.
But they came with significant long-term consequences.
Owning a stadium provides a club with a valuable asset.
Selling it may release money immediately, but it can also create rent obligations and reduce financial flexibility.
The same principle applies to training facilities.
Leeds had reached the point where selling players was no longer sufficient.
It was disposing of property assets to support the business.
The stadium sale became one of the clearest symbols of the collapse.
Elland Road had been associated with the club’s greatest achievements.
Now it was being used as part of a financial rescue strategy.
The decision illustrated how far Leeds had moved from its Champions League ambitions.
Administration in 2007 sent Leeds into the third division
The financial problems continued after relegation.
Leeds changed ownership again.
Ken Bates acquired control of the club in 2005.
The team came close to returning to the Premier League in 2006 but lost the Championship playoff final to Watford.
The following season was disastrous.
Leeds struggled near the bottom of the table.
In May 2007, the club entered administration.
The Football League imposed a 10-point deduction.
Leeds were relegated to League One, the third tier of English football.
It was the first time in the club’s history that they had fallen so low.
The administration process also produced further disputes involving creditors and the club’s ownership.
Leeds subsequently faced an additional 15-point penalty at the beginning of the 2007-08 League One season over the circumstances of their return from administration.
The punishment made the task of rebuilding even more difficult.
The club that had faced Valencia in a Champions League semifinal six years earlier was now playing in the third division.
The scale of the decline was almost unprecedented for a club of its recent European stature.
The Leeds United collapse in numbers
| Financial or sporting milestone | Figure |
|---|---|
| Last English league title before the collapse | 1991-92 |
| UEFA Cup semifinal appearance | 2000 |
| Champions League semifinal appearance | 2001 |
| Premier League finish in 2001-02 | 5th |
| Long-term bond secured against future matchday income | £60 million |
| Bond term | 25 years |
| Rio Ferdinand sale to Manchester United | Approximately £30 million |
| Reported 2002-03 pretax loss | £49.5 million |
| Wages as a share of turnover in 2002-03 | Approximately 88% |
| Net debt reported in 2003 | Approximately £78 million |
| Liabilities reported around the 2004 rescue | Approximately £103 million |
| Premier League relegation | 2004 |
| Elland Road sale | 2004 |
| Administration | 2007 |
| Relegation to League One | 2007 |
| Return to the Premier League | 2020 |
| Years outside the Premier League | 16 |
The numbers show that Leeds’ crisis was not simply a failure to qualify for one competition.
It was a combination of expensive long-term commitments and an unstable revenue model.
The £60 million bond committed future stadium income.
The wage bill consumed an exceptionally high proportion of turnover.
The club’s debt remained substantial even after major player sales.
And relegation reduced revenue further.
Each development made the next stage of the collapse more difficult to avoid.
Did Leeds’ collapse lead directly to Financial Fair Play?
Leeds became one of the most frequently cited examples of the risks associated with excessive football spending.
Its collapse demonstrated how quickly a successful club could become financially unstable when it relied on uncertain future revenue.
But it would be inaccurate to claim that Leeds directly caused UEFA to introduce Financial Fair Play.
UEFA’s Financial Fair Play framework was approved in 2009 and implemented from 2011.
Its development reflected wider concerns about financial losses, debt and competitive sustainability across European football.
Leeds was one prominent example of those problems.
Other clubs had also experienced severe financial difficulties.
The collapse therefore contributed to the broader debate about football finances rather than serving as the sole trigger for regulatory reform.
The lessons remain relevant.
Borrowing can support investment.
But borrowing against uncertain future success creates substantial risk.
A club that assumes regular Champions League qualification may face serious difficulties if it finishes outside the qualifying places.
And a wage bill that consumes nearly all revenue leaves little capacity to absorb unexpected losses.
Leeds illustrated all three problems.
How Leeds eventually returned to the Premier League
The recovery took far longer than the collapse.
Leeds spent three seasons in League One before earning promotion to the Championship in 2010.
The club then remained in the second tier for another decade.
Different owners, managers and rebuilding projects failed to produce a sustained return to the Premier League.
The decisive breakthrough came under Marcelo Bielsa.
Appointed in 2018, the Argentine coach transformed the team’s playing style and competitive performance.
Leeds won the Championship in 2019-20.
They returned to the Premier League after a 16-year absence.
The promotion was a major moment for supporters who had experienced the club’s decline from Champions League contender to third-division side.
Leeds were relegated again in 2023.
They returned to the Premier League in 2025 after winning the Championship under Daniel Farke.
As of October 31, 2026, Leeds are competing in the 2026-27 Premier League season.
Their return demonstrates that the club survived its financial collapse.
But it also shows how long the consequences lasted.
The decisions made during the early 2000s helped create problems that affected the club for nearly two decades.
The biggest mistake was treating Champions League qualification as guaranteed income
Leeds United’s collapse is often summarized as a story about reckless spending.
That description captures part of the problem, but it misses the most important financial mechanism.
The club did not simply spend heavily because it wanted better players.
It committed to a financial structure that required continued sporting success.
Champions League participation generated substantial revenue.
Leeds expected that revenue to continue.
The club used borrowing and player-financing arrangements to accelerate investment.
It also allowed wages to rise to levels that were difficult to sustain without European competition.
When qualification failed, the income disappeared but the obligations remained.
The board attempted to respond by selling players.
Those sales reduced financial pressure but weakened the team.
The weaker team produced poorer results.
The resulting decline made a return to the Champions League increasingly unlikely.
The club eventually lost its Premier League status, sold major assets and entered administration.
That sequence explains why Leeds’ collapse remains one of football’s most important financial cautionary tales.
The mistake was not ambition itself.
It was building a business that could survive only if ambition consistently turned into success.
+ Siga o Giro no Facebook
+ Siga o Giro no Instagram
Leia Mais: